Kenya Makes Digital Marine Cargo Insurance Mandatory from November 1: Without This One Certificate, Vehicles Cannot Clear Customs Even After Arrival at Port
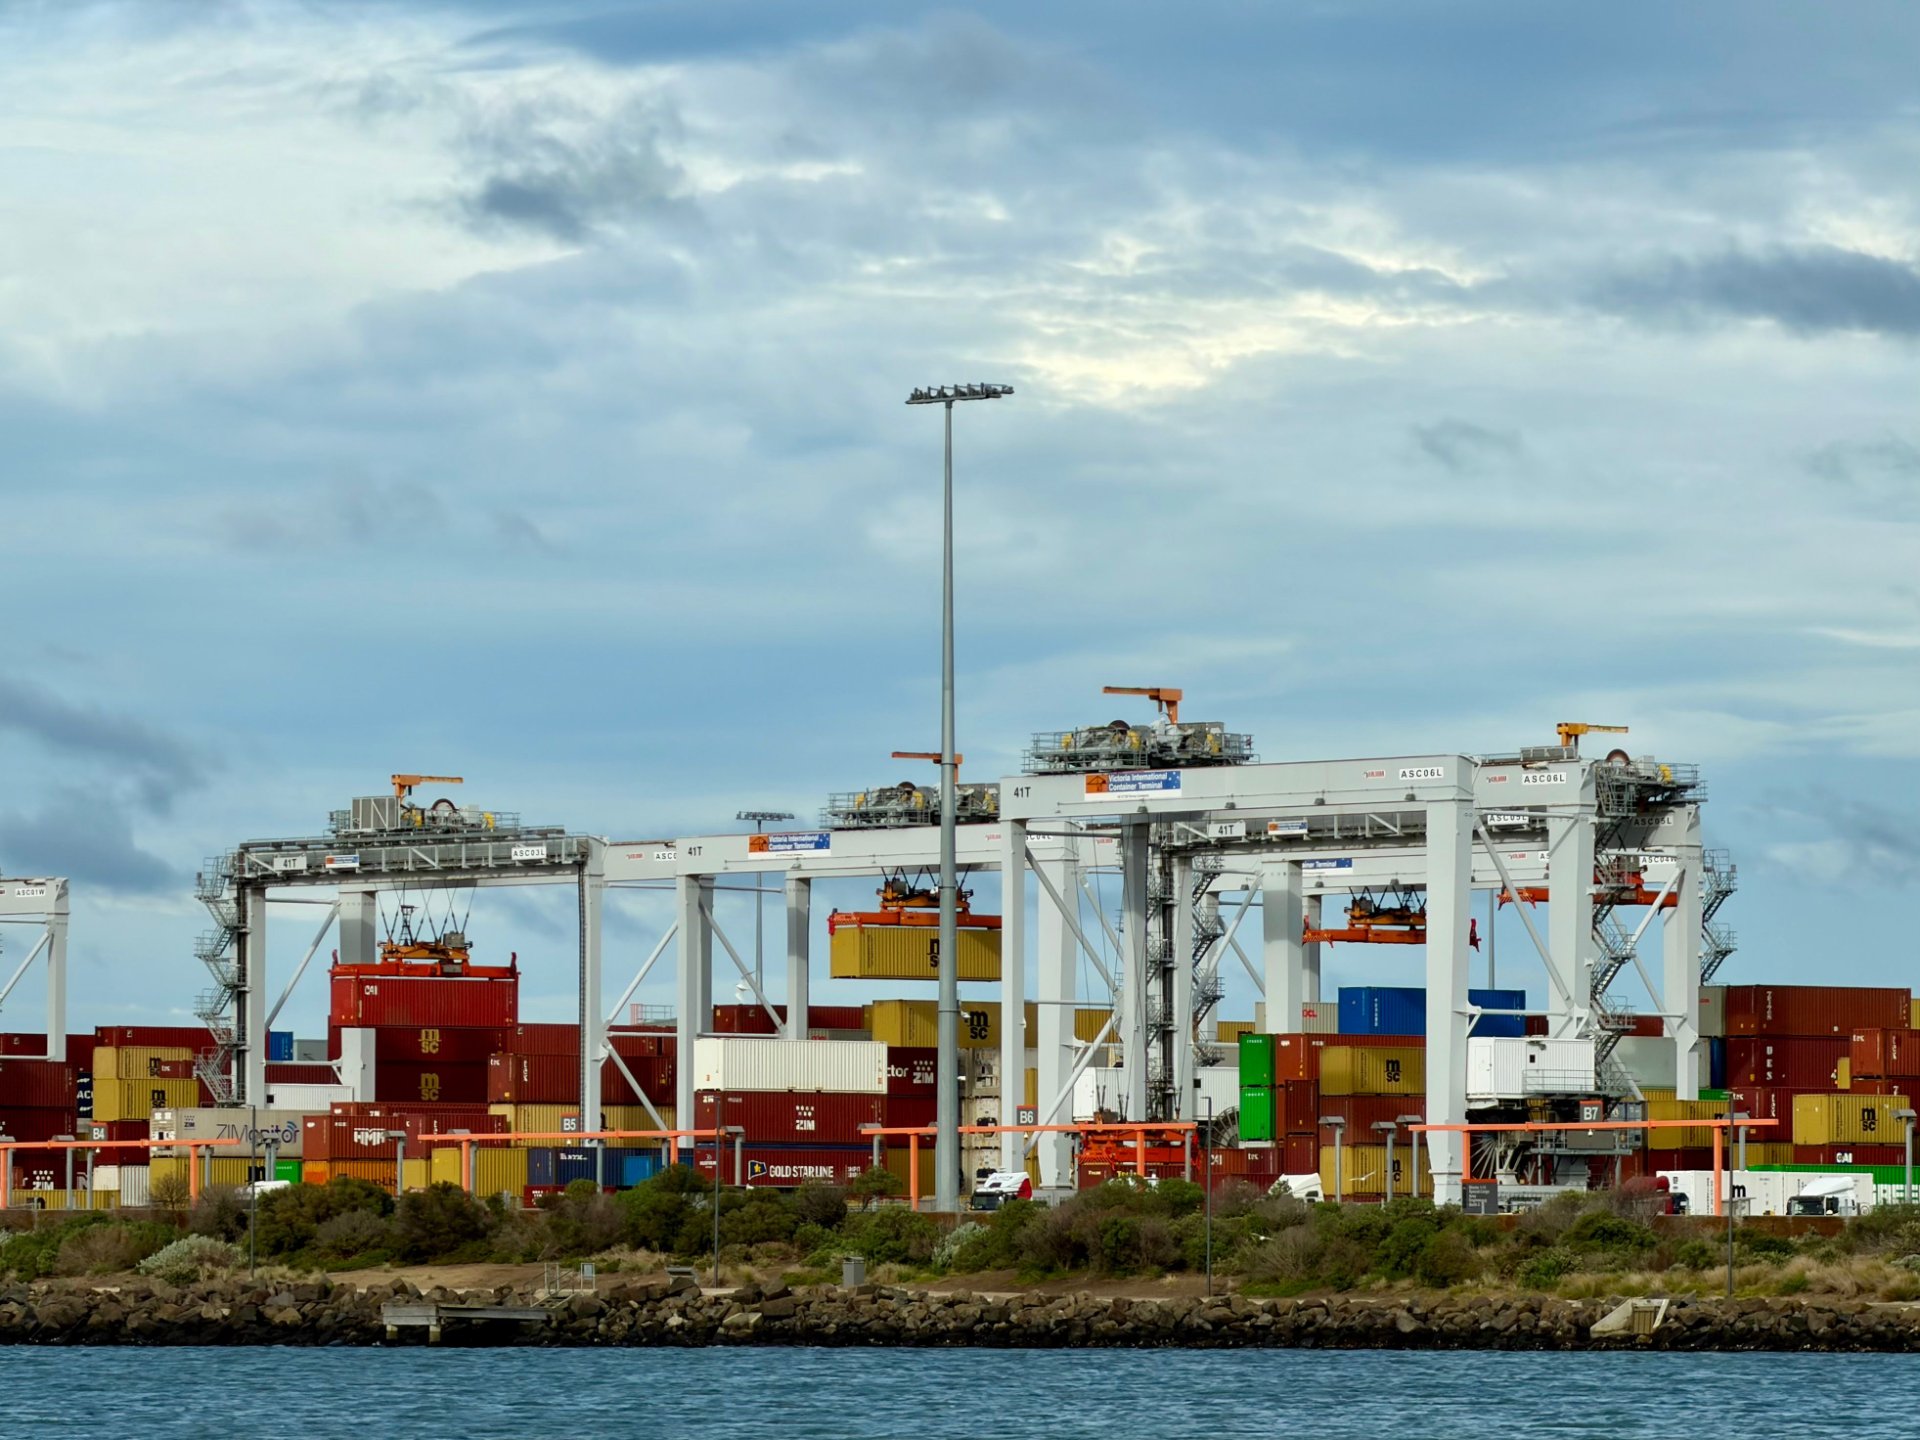
On November 1, 2026, the mandatory order for Digital Marine Cargo Insurance jointly introduced by the Kenya Revenue Authority (KRA) and the Insurance Regulatory Authority (IRA) officially took effect. From that day on, all imported vehicles shipped to Kenya must, before customs declaration, obtain a marine cargo insurance certificate issued by an IRA-licensed insurance company and have it connected to the KRA customs system through the digital system. Without this certificate, vehicles cannot clear customs after arriving at port.
For Chinese used-vehicle export enterprises serving the East African market, this is not a minor matter of "buying one more insurance policy." The key point is that the CIF marine insurance you buy in China or Japan is not recognized in Kenya’s customs system.
1. The Core Logic of the New Rule: Insurance Must Come from a Kenya-Licensed Insurance Company
According to the notice issued by KRA on October 22, from November 1, all goods entering Kenya must hold a valid marine insurance policy issued by an IRA-licensed insurance company. The certificate must be processed through the Digital Marine Cargo Insurance System (Digital MCI System) and enter KRA’s iCMS customs system before the customs broker submits the customs declaration. Goods that do not meet this condition will be blocked from clearance.
The most common pitfall here is that the marine insurance included in the CIF price cannot replace this certificate required by Kenya. The marine insurance purchased when shipping from Japan or China has an underwriter outside the IRA regulatory framework of Kenya and is therefore not recognized by KRA. What Kenya requires is a separate insurance policy issued by a local licensed insurance company, running in parallel with the CIF insurance purchased in the exporting country rather than replacing it.
From the practical timeline perspective, this certificate is usually handled together with the preparation of the Import Declaration Form (IDF) by the Kenyan customs broker, and the premium is calculated on the vehicle’s customs value (CIF value). Some customs brokers report that the premium for a Toyota Prado is around 4,000 Kenyan shillings, but this is only a case reference; the actual cost depends on the vehicle value and the insurance company.
2. What This Means for Used-Vehicle Exports
Kenya is an important used-vehicle import market in East Africa, with monthly imports usually between 4,000 and 7,000 units and up to about 9,000 units at peak times. Chinese vehicle sources face a right-hand-drive barrier in the Kenyan market itself (Kenya is a right-hand-drive country), but some enterprises still participate in this market through right-hand-drive source channels or transshipment via third countries. For these enterprises, the impact of the new rule is direct: there is one more precondition in the clearance chain, and this condition cannot be satisfied with insurance on the export side.
Specifically, export enterprises need to confirm two things before shipment: first, whether the local Kenyan importer or customs broker has already connected with an IRA-licensed insurance company and can complete the certificate before customs declaration; second, the certificate must enter the iCMS system before the customs declaration — if you wait until the vehicle arrives at port to apply for it, it will already be too late.
Kenya’s clearance system has been continuously upgraded digitally in recent years. From IDF to iCMS and now to the digital marine insurance system, data across the various stages is being connected. This means the operational space that may have existed in the past for "clearing first and submitting documents later" is being systematically compressed.
3. Viewed Within the Overall East African Market Picture
Kenya’s new insurance rule this time is not an isolated policy action. Since 2026, regulatory tightening in the East African market has been advancing on multiple fronts: Kenya itself is pursuing a long-term plan to phase out used-vehicle imports by 2030, with the age ceiling to be gradually compressed from 8 years to 5 years, then 3 years, and finally to zero; Uganda, in its FY2026/27 proposal, lowers the age ceiling from 15 years to 13 years and imposes a tiered environmental tax of 10% to 50% on vehicles older than 9 years; Tanzania, from July 1, levies excise duty on imported used vehicles in age bands, with a rate of 18% for vehicles 8 to 10 years old and a jump to 35% for those over 10 years.
What these policies point to in common is that the threshold for accepting used vehicles in the East African right-hand-drive market keeps rising, and the approach is becoming increasingly systematic — no longer a single age limit, but simultaneous tightening across insurance, certification, taxes and fees, and digital customs declaration.
For Chinese used-vehicle export enterprises whose sources are mainly left-hand-drive, the structural barrier of the East African market (right-hand drive) already exists, and with these compliance requirements layered on, the cost of entry rises further. The West African left-hand-drive market (Nigeria, Ghana, Benin, Togo and others) remains the main battleground better suited to Chinese sources, but West Africa is itself experiencing policy fluctuations (mandatory enforcement of VehCAP in Nigeria, and Ghana’s PVoC remaining unresolved after being suspended), so export enterprises need to treat "destination-country compliance certainty" as an important variable in product selection and scheduling.
Kenya’s mandatory digital marine insurance order is essentially a tightening of clearance preconditions. It does not change Kenya’s access standards for used vehicles themselves, but it makes the operating model of "figure something out once the car arrives" completely ineffective. For export enterprises still participating in the Kenyan market, confirming with local customs brokers the process and timing for obtaining IRA-licensed insurance is the most urgent practical matter at present. For Chinese export enterprises whose sources are mainly left-hand-drive, the greater significance of this matter is the reminder that every compliance threshold in the East African right-hand-drive market is screening out enterprises that cannot complete all pre-shipment preparations before dispatch.